Risk Management and Financing Problems of Startups in Algeria: What Role Does Bancassurance Play? (Economía & Negocios)
Summary
- Startups in Algeria face high operational risks and financial constraints, with a failure rate between 60 % and 90 %, and around 10 % failing during their first year of existence.p.3
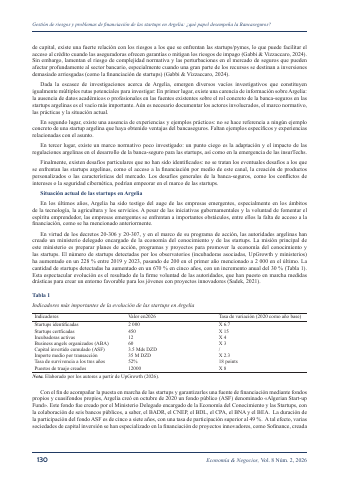
- The number of identified startups in Algeria grew by 228 % between 2019 and 2023, expanding from 200 to 2 000 enterprises.p.4
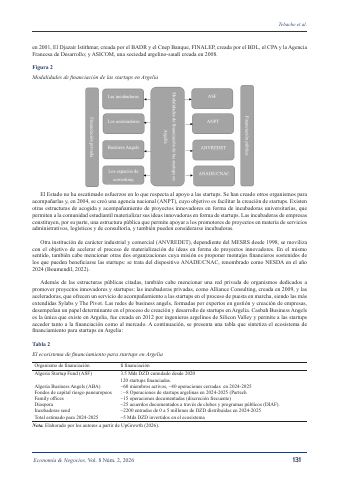
- The public Algeria Startup Fund (ASF) accumulated 3.5 Mds DZD in invested capital since 2020, backing 120 startups.p.5
- Total funding deployed across the Algerian startup ecosystem in 2024-2025 is estimated at ~5 Mds DZD from public funds, business angels, and venture capital.p.5
- Commercial bank lending to startups remains highly restricted due to collateral scarcity, as market data indicates only 30 % of startups succeed.p.6
- Insurance companies operating in partnership with banks could generate an estimated annual investment liquidity of 19 000 millones de dinares for economic sector financing.p.8
- Administrative processing times for combined bank and insurance financing applications can extend up to 90 días, limiting business agility.p.11
Key insights
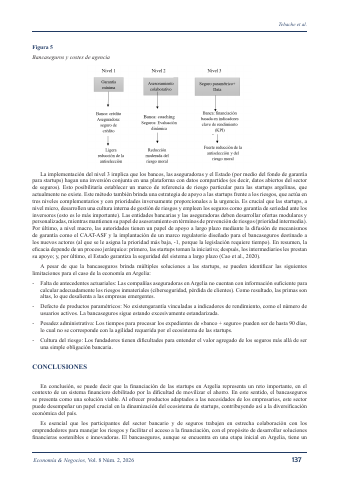
- Bancassurance functions as a strategic governance mechanism that reduces agency costs through ex-ante risk signaling and ex-post operational monitoring.p.3
- Severe information asymmetries between startup founders and financial institutions force entrepreneurs to rely heavily on limited self-funding or informal sources.p.3
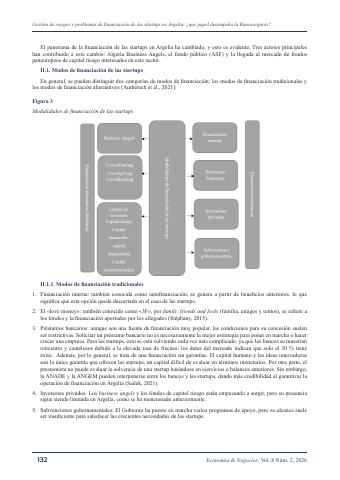
- Traditional bank loans are unsuitable for early-stage startups because banks cannot easily monetize human capital and innovative concepts as physical collateral.p.6
- Algerian regulatory frameworks require insurance providers to invest 50 % of their regulated commitments into low-risk state securities.p.8
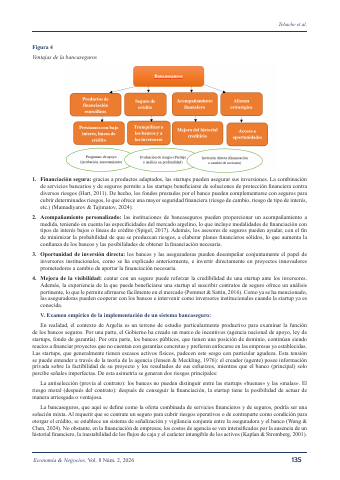
- By offering combined bank-insurance products, financial institutions can act directly as institutional investors into unlisted early-stage growth startups.p.9
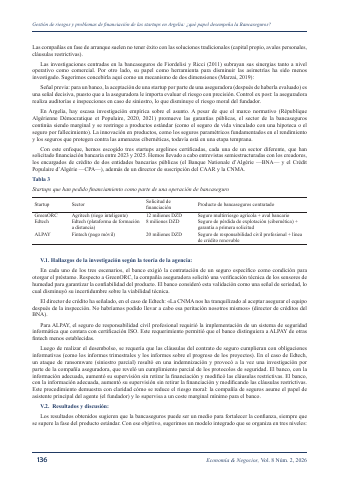
- Empirical case studies of Algerian startups demonstrate that insurance coverage for cyber, agricultural, or professional liabilities facilitates bank credit approvals.p.10
- The lack of historical actuarial data on intangible assets in Algeria results in elevated insurance premiums that discourage startup adoption.p.11
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
Topics and entities
BankingInsuranceInsurtechPublic funding and grantsSME finance and lendingStartup ecosystemsStartup fundingVenture capitalAlgeria Business Angels (ABA)Algeria Startup Fund (ASF)Alliance AssurancesALPAYBank of AlgeriaBanque Nationale d’Algérie (BNA)CAARCasbah Business AngelsCNMACrédit Populaire d’Algérie (CPA)GreenORC
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.