Digital Infrastructure Integration and Capital-Market Resilience in a Frontier Exchange: A Longitudinal Panel and Coefficient-Decomposition Analysis of the Nairobi Securities Exchange (Cureus Journal of Business and Economics.)
Summary
- The study analyzes a balanced panel of 53 ordinary equity securities continuously listed and traded on the Nairobi Securities Exchange over the 2021-2025 period.p.5
- Sub-Saharan Africa represents the global center of mobile money, processing approximately USD 1.4 trillion in transactions in 2025.p.3
- During the macroeconomic stress period of 2023, the Kenyan shilling experienced a year-on-year depreciation of 20.4% against the US dollar under monetary tightening.p.2
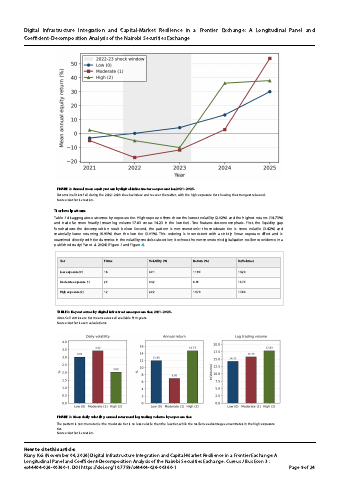
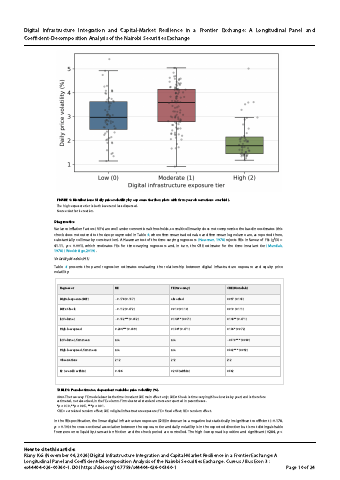
- Firms in the high digital exposure tier recorded lower daily price volatility of 2.02% and higher average returns of 14.73% compared to traditional sector counterparts.p.9
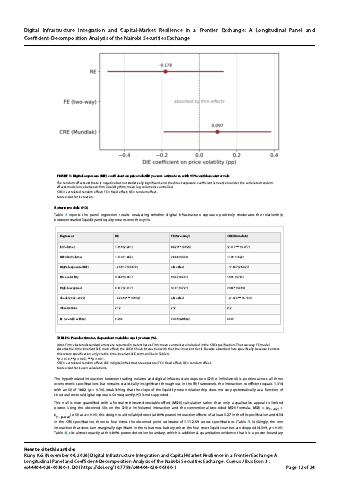
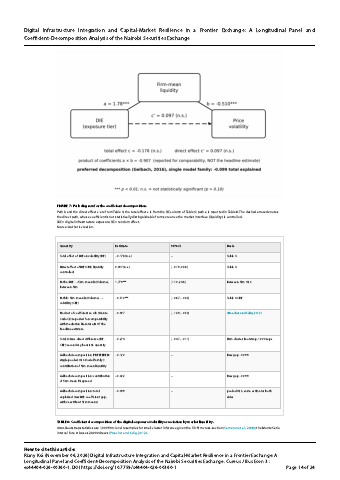
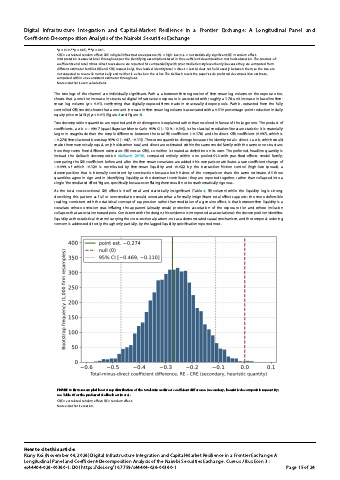
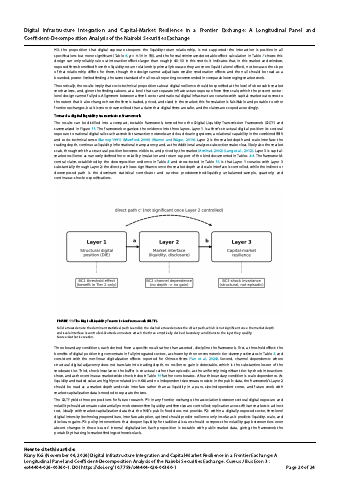
- A Gelbach decomposition attributes −0.120 of the −0.099 total raw DIE coefficient gap directly to between-firm market liquidity.p.1
- Descriptive statistics across 212 firm-year observations show an average annual logarithmic equity return of 10.22% and a mean daily price volatility of 2.98%.p.8
Key insights
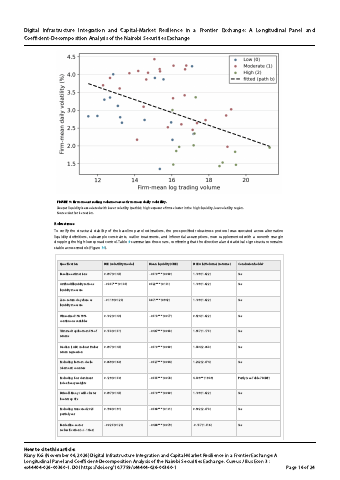
- Market liquidity, rather than direct digital exposure, carries the primary association with equity price volatility during market shocks.p.1
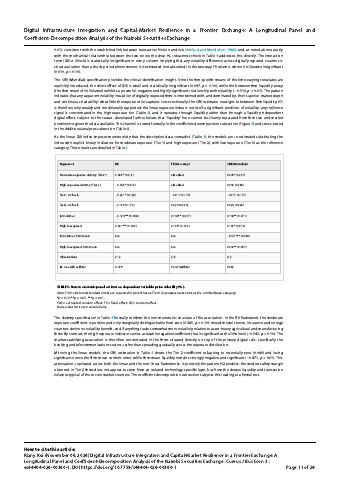
- A Hausman specification test strongly rejects random effects in favor of fixed effects for time-varying regressors with a test statistic of χ²(3) = 41.11 (p < 0.001).p.7
- High digital exposure firms exhibited lower price volatility of 2.02% compared to 3.42% for moderate exposure and 3.01% for low exposure firms.p.9
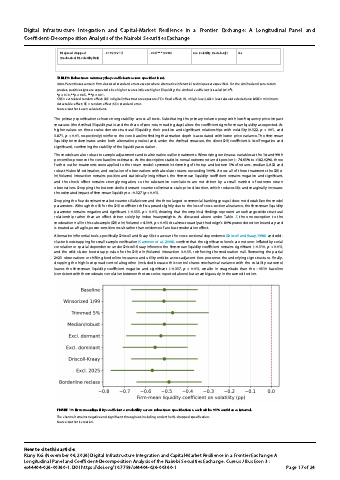
- In the correlated random effects model, the direct effect of digital infrastructure exposure on price volatility is statistically insignificant at 0.097 when controlling for firm-mean liquidity.p.10
- Gelbach coefficient decomposition confirms that firm-mean log trading volume contributes −0.120 of the −0.099 raw coefficient change across models.p.14
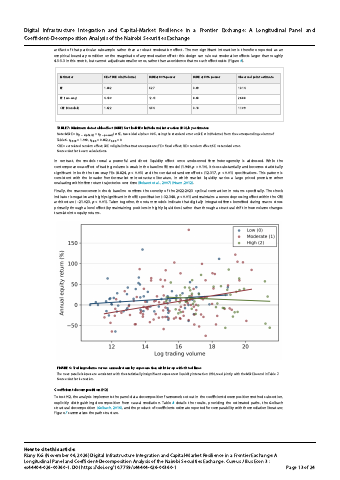
- Hypothesized moderation where digital exposure steepens the volume-return relationship was not supported, as interaction terms remained statistically insignificant across all specifications.p.12
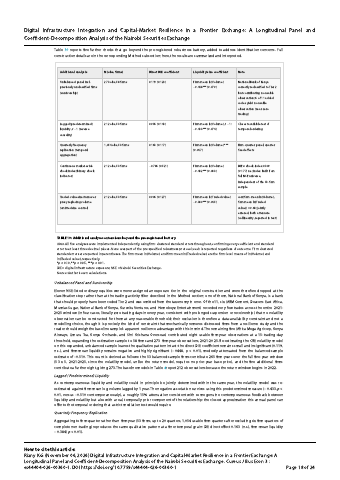
- Re-estimating the volatility model on an expanded unbalanced sample of 58 firms confirms the market liquidity channel with a firm-mean log volume coefficient of −0.448 (p < 0.01).p.18
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
 p.20
 p.21
 p.22
 p.23
 p.24
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.