Inflation, Exchange Rate Movements and Cryptocurrency Returns in Nigeria: Evidence from a Structural VAR Model (Zenodo (CERN European Organization for Nuclear Research))
Summary
- The paper investigates the dynamic relationships between headline inflation, official naira/US-dollar exchange rate, and returns of five cryptocurrencies using a seven-variable structural vector autoregressive (SVAR) model.p.1
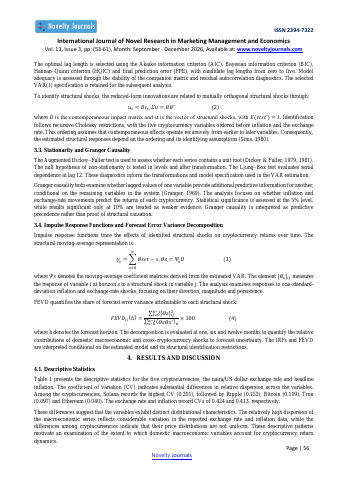
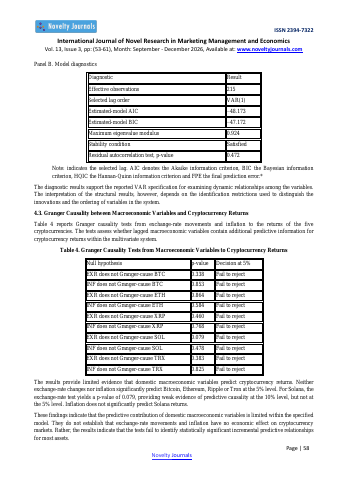
- All lag-order selection criteria (AIC, BIC, HQIC, FPE) unanimously select a VAR(1) specification, yielding an estimated-model AIC of −48.173 and a maximum eigenvalue modulus of 0.924.p.6
- Granger causality tests show limited predictive evidence from domestic macroeconomic variables to cryptocurrency returns at the 5% significance level, with exchange-rate changes providing weak predictive evidence for Solana at a p-value of 0.079.p.6
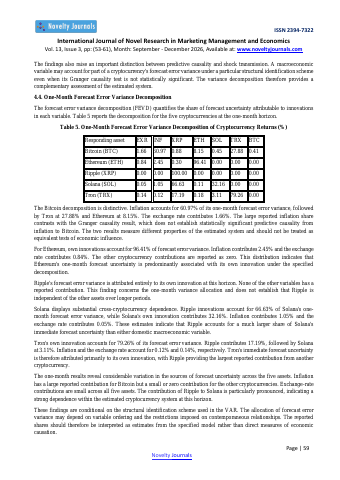
- In the one-month forecast error variance decomposition, headline inflation accounts for 60.97% of Bitcoin's forecast error variance, while Tron accounts for 27.88%.p.7
- Ripple innovations explain 66.63% of Solana's one-month forecast error variance, while Solana's own innovation accounts for 32.16%.p.7
Key insights
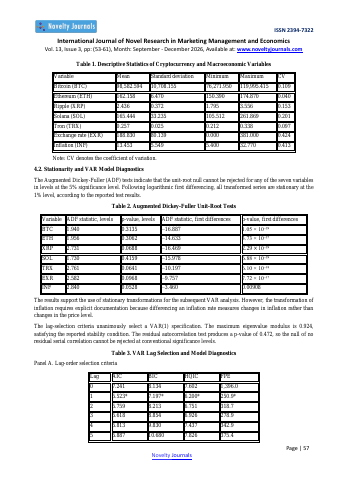
- All seven analyzed time series contain unit roots in levels but achieve stationarity after first differencing.p.5
- Lag selection criteria unanimously select a VAR(1) specification that satisfies structural stability with a maximum eigenvalue modulus of 0.924.p.5
- Granger causality tests fail to reject the null hypothesis of non-causality from domestic inflation and exchange rates to cryptocurrency returns at the 5% level.p.6
- Exchange-rate movements exhibit weak predictive power for Solana returns, yielding a p-value of 0.079 at the 10% significance level.p.6
- Headline inflation accounts for a prominent 60.97% of Bitcoin's one-month forecast error variance.p.7
- Ripple innovations exert a strong influence on Solana, accounting for 66.63% of its one-month forecast uncertainty compared to 32.16% from Solana's own innovation.p.7
- Tron's one-month forecast error variance is dominated by its own innovation at 79.26%, with Ripple providing the largest cross-cryptocurrency contribution at 17.19%.p.7
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.