Federal Reserve Monetary Policy Changes and Short-Term Bitcoin Returns: An Event Study Analysis of FOMC Rate Actions (Advances in Economics Management and Political Sciences)
Summary
- The empirical analysis examines 26 FOMC rate-change announcements from 2017 through 2024, comprising 18 rate hikes and 8 rate cuts.p.2
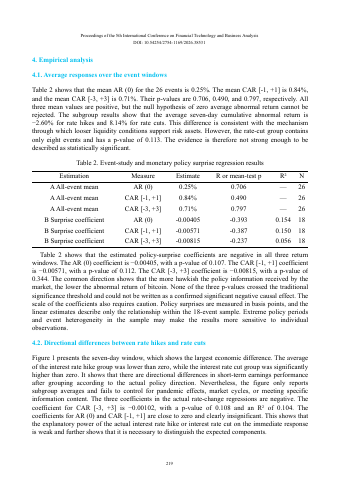
- Across all 26 events, the mean event-day abnormal return AR (0) for Bitcoin is 0.25% with a p-value of 0.706.p.5
- The mean three-day cumulative abnormal return CAR [-1, +1] across all events is 0.84% with a p-value of 0.490.p.5
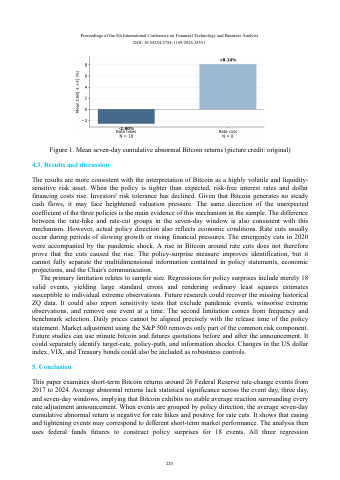
- Subgroup analysis reveals a mean seven-day CAR [-3, +3] of −2.60% for interest rate hikes compared to 8.14% for rate cuts.p.5
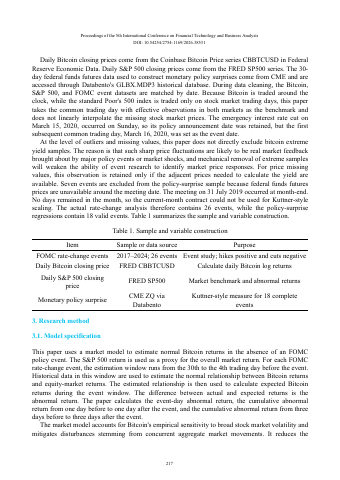
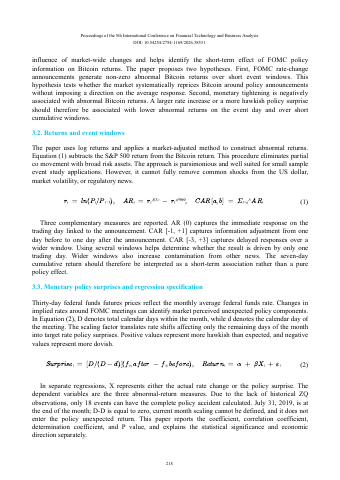
- Using 30-day federal funds futures, 18 complete monetary policy surprise measures were constructed to isolate unexpected policy shifts.p.3
Key insights
- Average abnormal Bitcoin returns across all 26 FOMC rate-change events do not show statistically significant deviation from zero.p.5
- Grouped by policy direction, rate cuts generate positive average seven-day cumulative abnormal returns while rate hikes yield negative ones.p.5
- Federal funds futures data enabled the quantification of 18 observable monetary policy surprises using the Kuttner scaling method.p.3
- Regression coefficients for unexpected policy surprises are consistently negative across event-day, three-day, and seven-day windows.p.5
- Actual nominal interest rate adjustments display lower explanatory power for immediate Bitcoin price reactions than unexpected policy surprises.p.5
- The empirical results support viewing Bitcoin as a high-volatility risk asset sensitive to broader US dollar liquidity and policy tightening.p.6
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.