The Effect of Fraud Hexagon Theory on Financial Statement Fraud with Audit Committee as a Moderating Variable (Jurnal Riset Akuntansi)
Summary
- The study analyzes state-owned enterprises (SOEs) listed on the Indonesia Stock Exchange during the 2018–2023 period.p.1
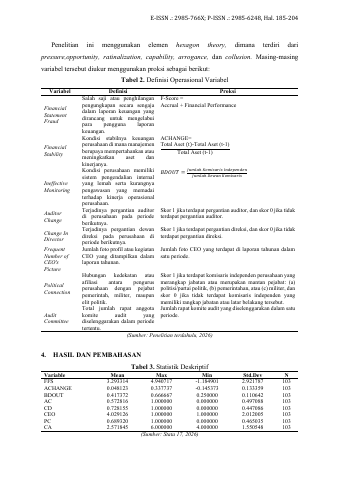
- The analysis utilizes a final sample of 103 firm-year observation data points after filtering outliers from an initial set of 120 data points.p.8
- A case involving PT Indofarma Tbk revealed financial irregularities that caused losses to the state amounting to Rp371.834.530.652.p.2
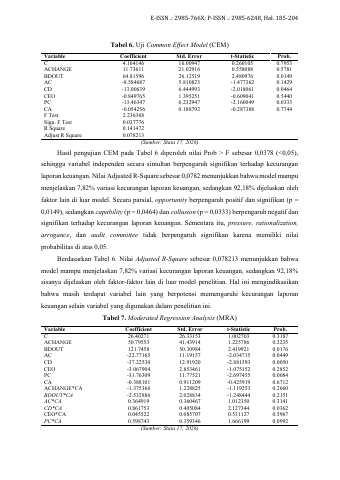
- The regression model yields an Adjusted R-Square value of 0.0782, indicating that the independent variables explain 7.82% of the variation in financial statement fraud.p.11
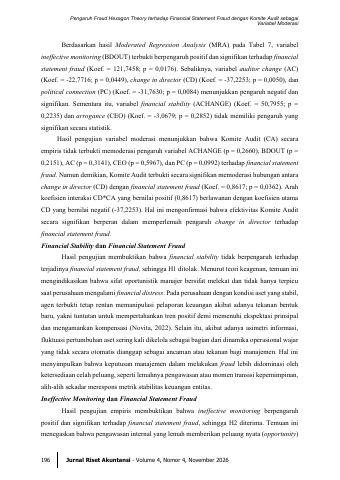
- Ineffective monitoring has a significant positive coefficient of 121.7458 on financial statement fraud with p = 0.0176.p.12
- The interaction between change in director and audit committee is statistically significant with a coefficient of 0.8617 and p = 0.0362.p.12
Key insights
- Ineffective monitoring significantly increases the likelihood of financial statement fraud in Indonesian SOEs.p.1
- Director changes and political connections show significant negative effects on financial statement fraud.p.1
- Financial stability, auditor change, and the frequency of CEO pictures do not have a statistically significant direct impact on financial statement fraud.p.1
- Audit committee activity only moderates the relationship between change in director and financial statement fraud.p.1
- PT Indofarma Tbk generated a state loss of Rp371.834.530.652 due to fictitious procurement and debt recording manipulation.p.2
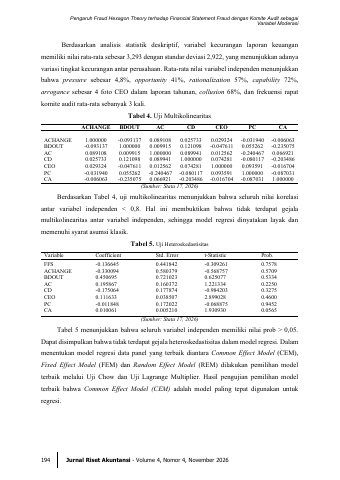
- The Common Effect Model was determined as the most suitable panel regression estimation method based on model selection tests.p.10
- Audit committee meetings effectively weaken the negative impact of director turnover on financial statement fraud risks.p.12
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
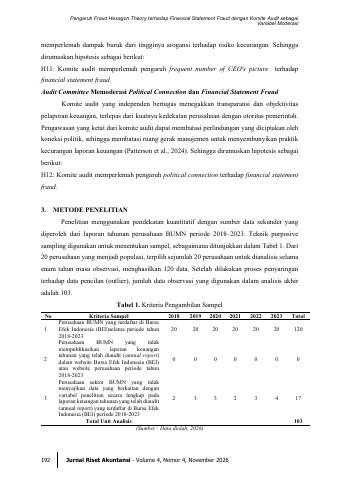 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
 p.19
 p.20
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.