Optimization of Dynamic Crypto Portfolios via Deep Reinforcement Learning Under Transaction Costs (Research Square)
Summary
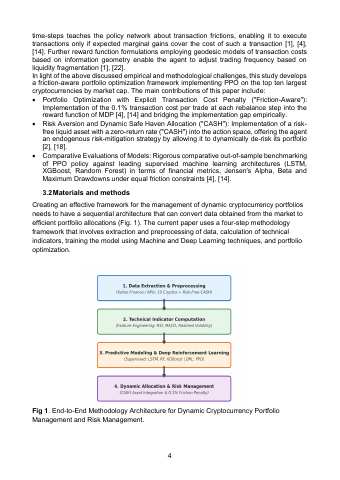
- The DRL-PPO strategy generated an annualized return of 37.22% under a 0.1% transaction cost constraint.p.2
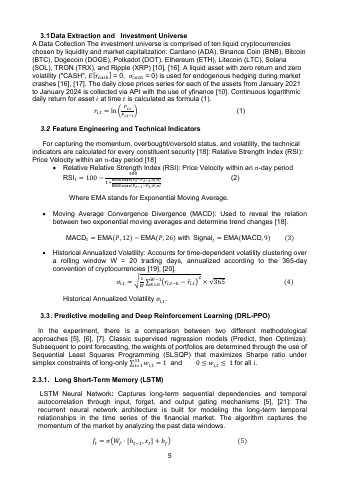
- The tested universe comprised 10 liquid cryptocurrencies analyzed over daily price series from January 2021 to January 2024.p.6
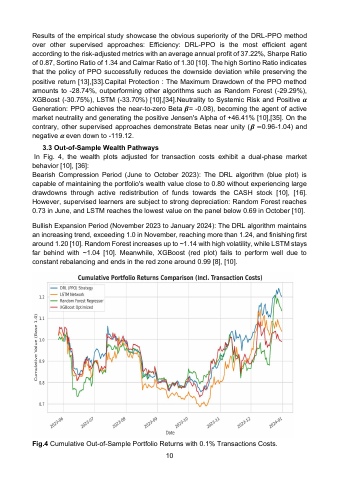
- DRL-PPO achieved the lowest maximum drawdown among all evaluated strategies at -28.74%.p.10
Key insights
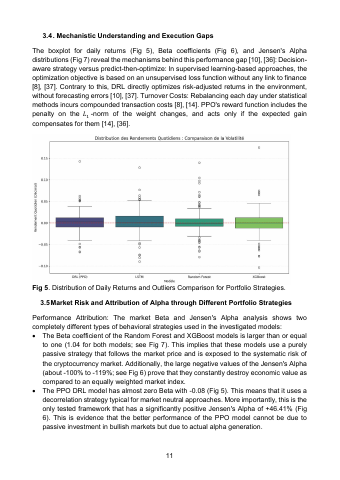
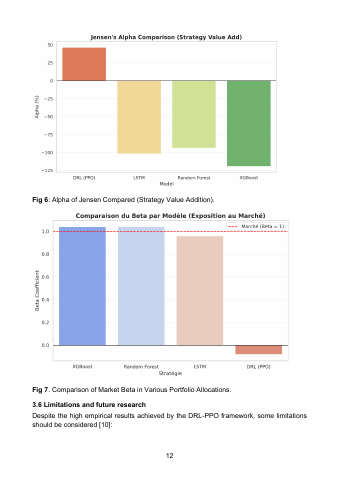
- DRL-PPO achieved market neutrality with a beta of -0.08 and generated a positive Jensen's alpha of 46.41%.p.2
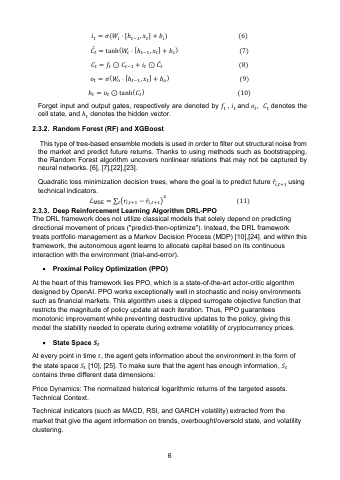
- Supervised predictive models exhibited market betas near unity, leaving portfolios exposed to systematic market downturns.p.2
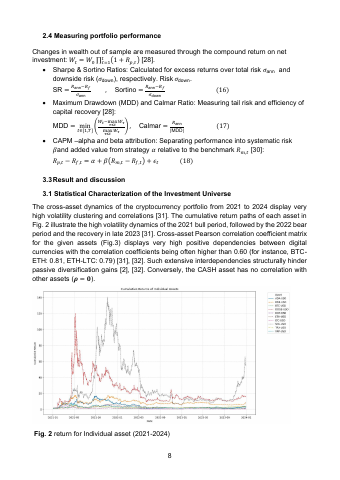
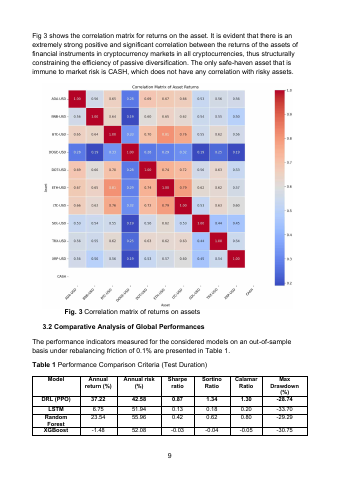
- Cryptocurrency market assets display cross-asset correlation coefficients frequently exceeding 0.60, limiting the benefits of passive diversification.p.9
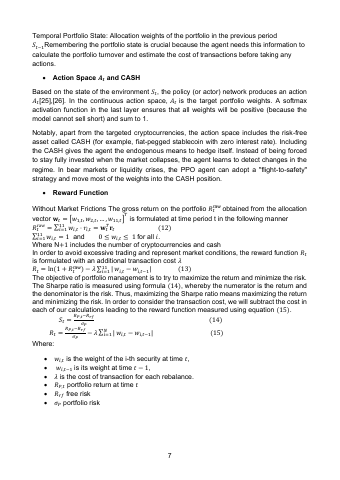
- Adding a zero-return risk-free CASH asset to the action space provides endogenous portfolio hedging during severe bear markets.p.8
- Explicitly penalizing transaction frictions within the DRL reward function prevents over-trading and mitigates turnover drag.p.3
- Traditional predict-then-optimize frameworks degrade net performance because point-forecasting errors spur excessive rebalancing.p.3
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
 p.17
 p.18
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.