Front-End Rates and Long-End Relative Value in the U.S. Treasury Curve (Research Square)
Summary
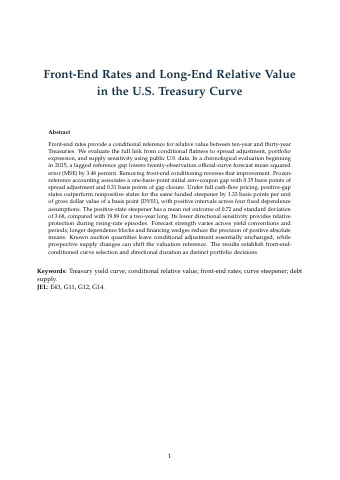
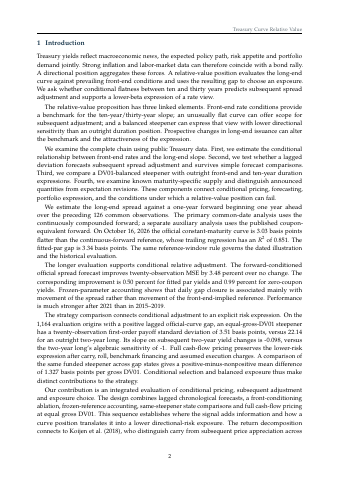
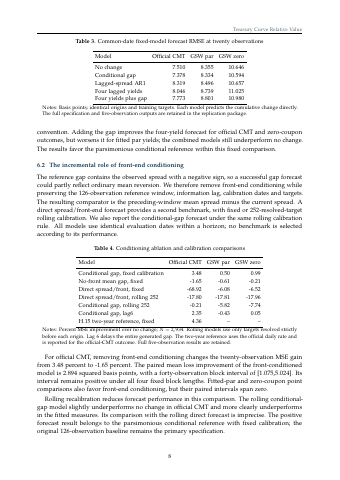
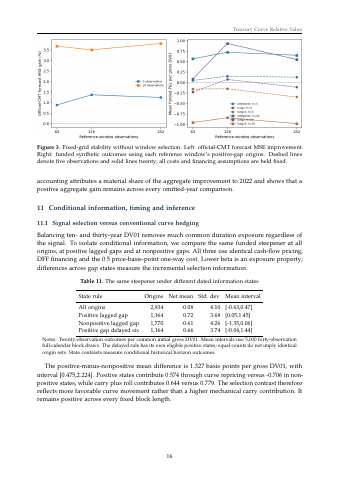
- A lagged reference gap lowers twenty-observation official-curve forecast mean squared error (MSE) by 3.48 percent.p.2
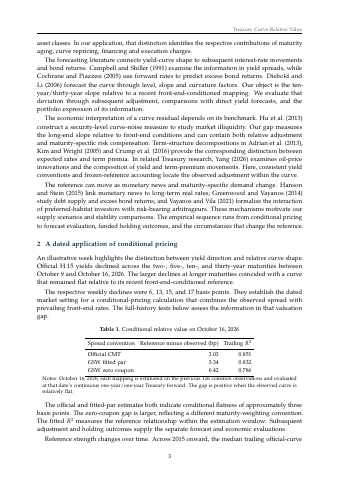
- On October 16, 2026, the official constant-maturity curve was 3.03 basis points flatter than the continuous-forward reference.p.3
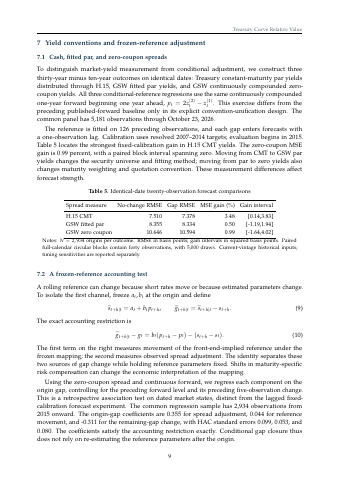
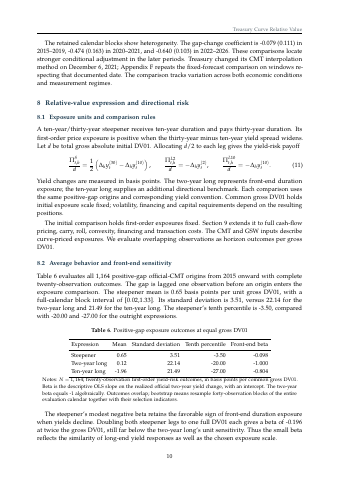
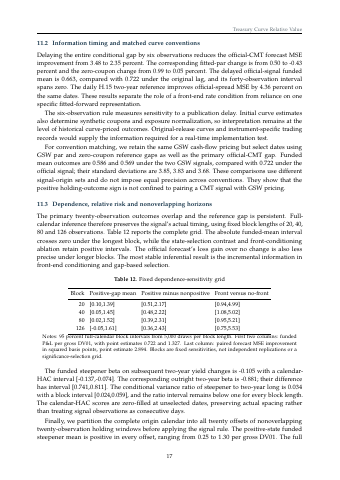
- For 1,164 positive-gap official-CMT origins from 2015 onward, an equal-gross-DV01 steepener had a payoff standard deviation of 3.51 basis points, compared with 22.14 for an outright two-year long.p.3
Key insights
- Front-end rate conditions establish a conditional relative-value benchmark for ten-year versus thirty-year Treasury spreads.p.2
- Frozen-reference accounting demonstrates that daily alignment closure is primarily driven by spread adjustment rather than reference parameter shifts.p.9
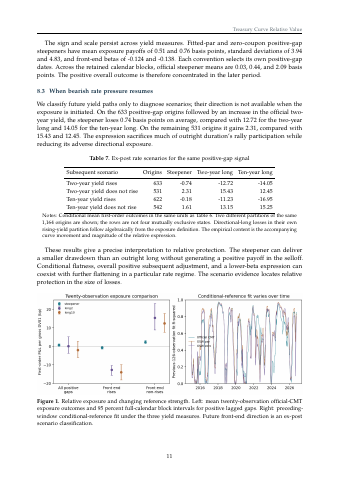
- An equal-gross-DV01 steepener provides relative protection during rising-rate episodes by sacrificing directional rally participation to reduce drawdown size.p.11
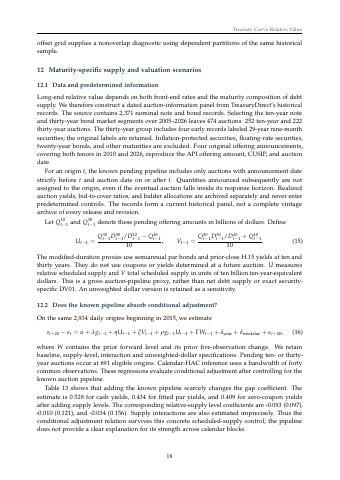
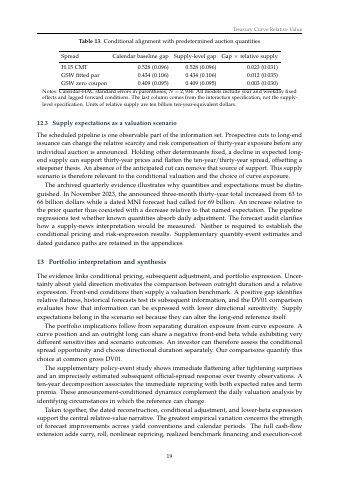
- Routine scheduled auction quantities do not absorb the conditional curve adjustment relationship.p.18
Pages
 p.1
 p.2
 p.3
 p.4
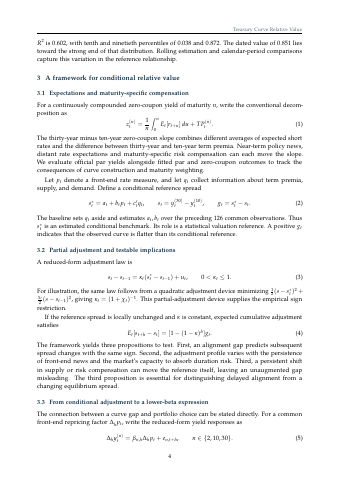 p.5
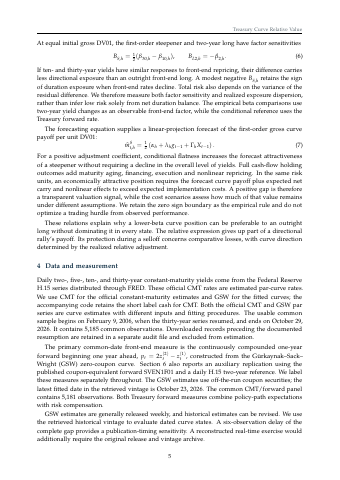 p.6
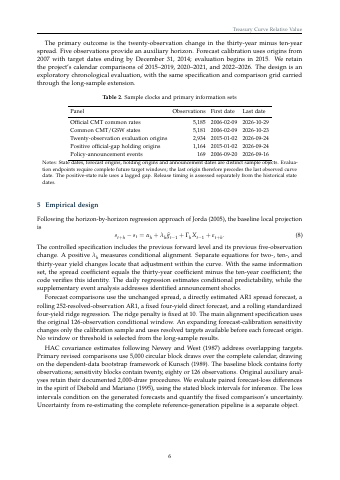 p.7
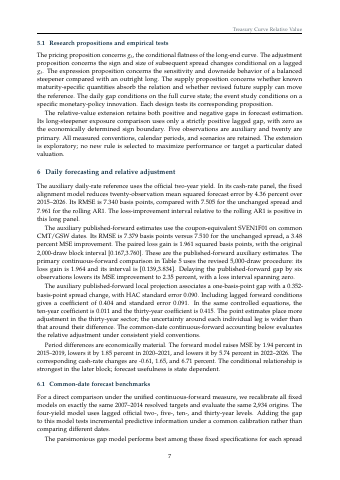 p.8
 p.9
 p.10
 p.11
 p.12
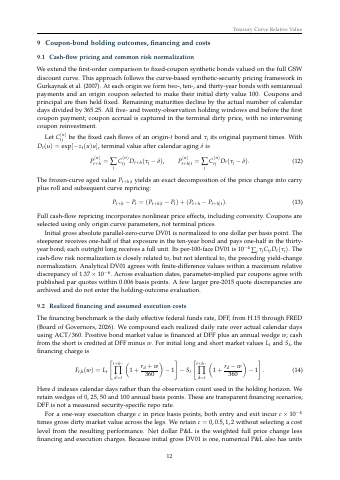 p.13
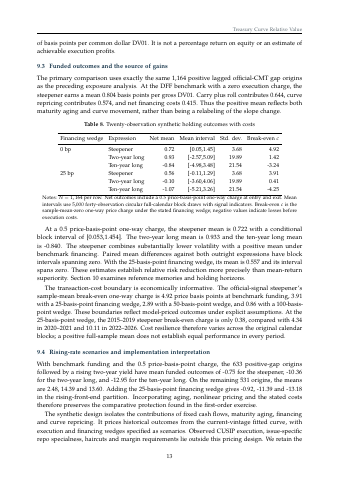 p.14
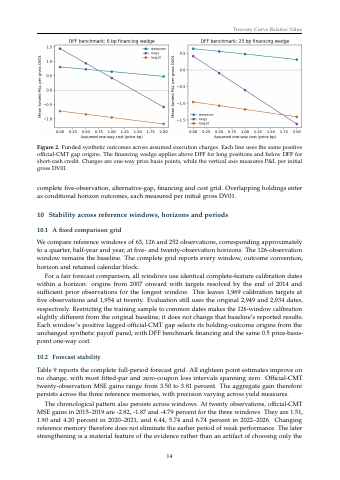 p.15
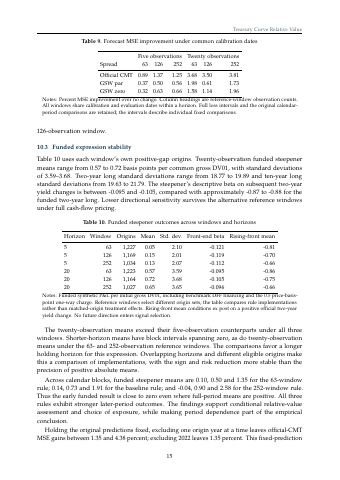 p.16
 p.17
 p.18
 p.19
 p.20
 p.21
 p.22
 p.23
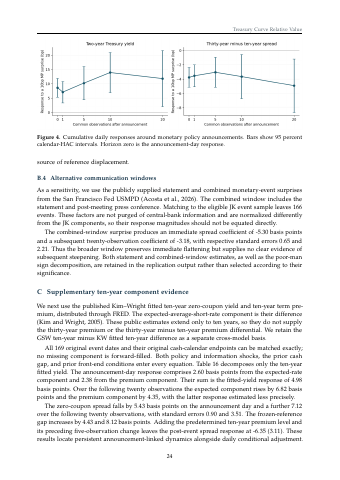
 p.24
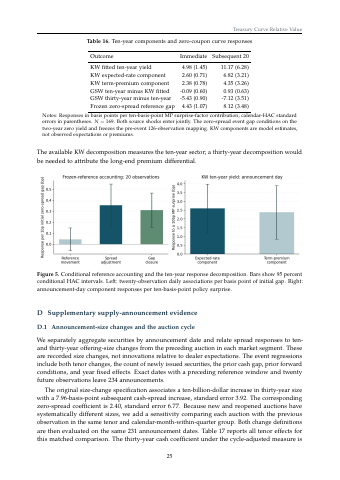
 p.25
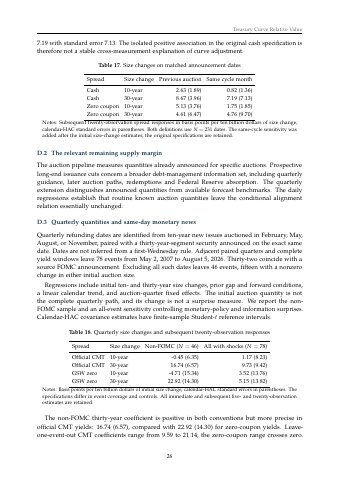
 p.26
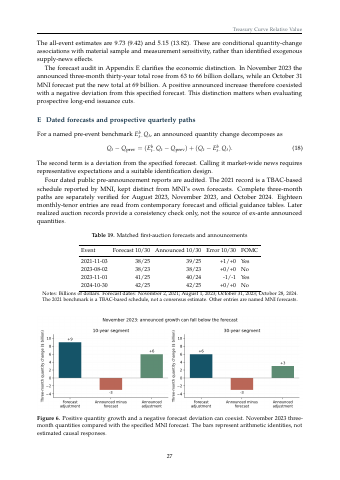
 p.27
 p.28
 p.29
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.