AI-Automated Financial Reporting, Accounting Quality, Internal Controls, and Equity Market Valuations: Documentary Evidence from GCC-Listed Companies (Computer and decision making.)
Summary
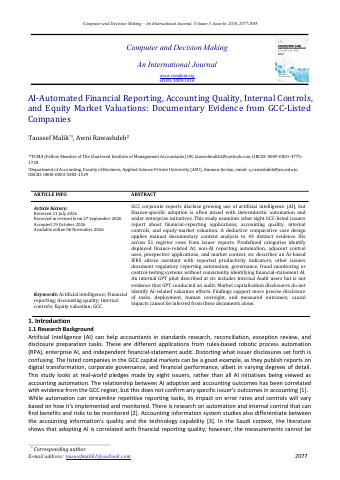
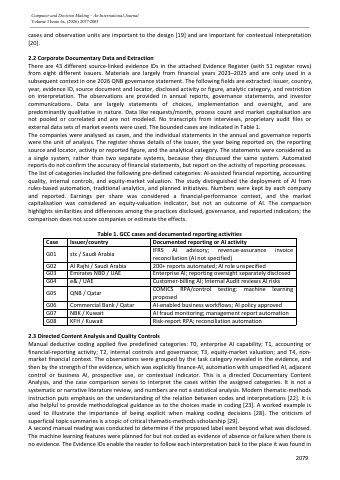
- The study applies manual documentary content analysis to 43 distinct source-linked evidence IDs across 51 register rows from GCC issuer reports.p.1
- stc deployed an AI-supported digital co-worker on IFRS that processes about 100 compliance requests every month.p.5
- stc reported a 70% increase in productivity for finance teams and resolved complex cases 33% quicker using its IFRS AI assistant.p.5
- stc disclosed an organization-wide data quality indicator of 97%.p.5
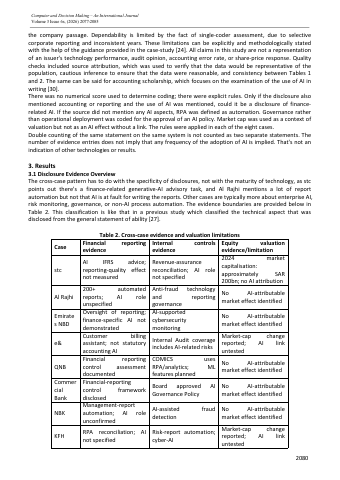
- Al Rajhi disclosed that over 200 strategic and regulatory reports were automated, though the AI role remained unspecified.p.5
- stc disclosed a 2024 market capitalisation of approximately SAR 200bn without attributing any valuation impact to AI.p.4
Key insights
- Finance-specific AI adoption in corporate disclosures is frequently mixed with deterministic process automation and general enterprise initiatives.p.1
- An internal GPT pilot at stc includes Internal Audit users but does not constitute evidence of GPT conducting financial audits.p.1
- Public annual and governance disclosures do not offer identified date-specific investor responses or direct causal links to equity market valuations.p.6
- QNB's COMICS platform employs RPA for automated control testing, while machine-learning capabilities are designated as prospective.p.5
- Disclosed automation in report generation does not exhibit documented reductions in financial restatements, abnormal accruals, or error rates.p.5
- Issuer disclosures would be more decision-useful by identifying specific reporting tasks, deployment dates, human reviewers, and validated outcomes.p.6
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.