The Effect of Tax Compliance Costs on MSME Taxpayer Compliance: Evidence from Sukoharjo Regency (Jurnal Ilmiah AccUsi)
Summary
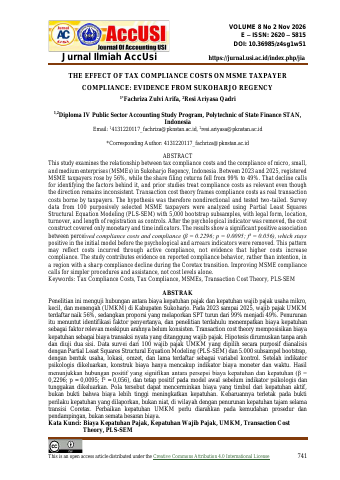
- Between 2023 and 2025, registered MSME taxpayers in Sukoharjo Regency rose by 56%, while the share filing tax returns fell from 99% to 49%.p.1
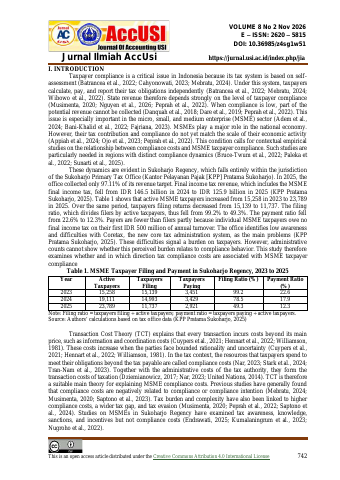
- Final income tax revenue collected by the Sukoharjo Primary Tax Office decreased from IDR 146.5 billion in 2024 to IDR 125.9 billion in 2025.p.2
- Active MSME taxpayers increased from 15,258 in 2023 to 23,789 in 2025, while the payment ratio declined from 22.6% to 12.3%.p.2
- A G*Power 3.1 analysis indicated a required minimum of 92 respondents, and the study gathered data from 100 valid questionnaires across 12 subdistricts.p.5
- Sole proprietorships made up 86% of the survey respondents, and 83% reported an annual business turnover of up to IDR 500 million.p.8
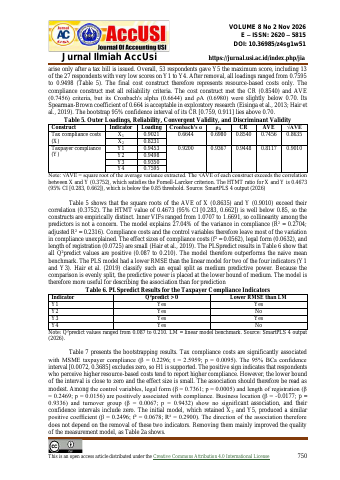
- The structural equation model explained 27.04% of the variance in taxpayer compliance (R² = 0.2704).p.10
Key insights
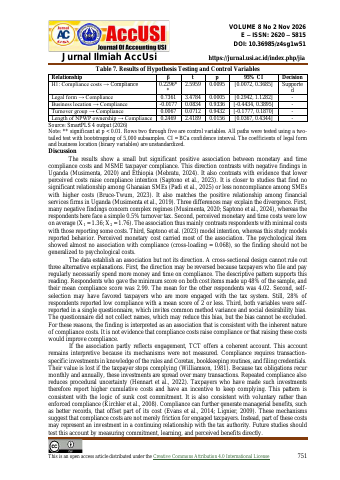
- PLS-SEM analysis identified a statistically significant positive association between perceived compliance costs and MSME taxpayer compliance (β = 0.2296; p = 0.0095; f² = 0.056).p.1
- In 2025, the Sukoharjo Primary Tax Office achieved 97.11% of its total revenue target.p.2
- The operational framework categorizes monetary outlays as explicit costs and spent time as implicit costs, while treating stress and anxiety as psychological costs.p.4
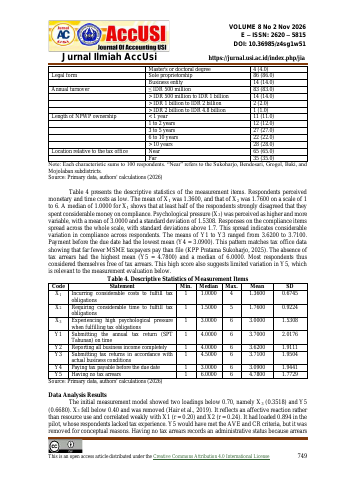
- On a 1 to 6 scale, respondents reported low average perceived monetary costs (1.3600) and time costs (1.7600), but higher psychological pressure (3.0000).p.9
- Among the control variables, legal form (β = 0.7361; p = 0.0005) and length of tax registration (β = 0.2469; p = 0.0156) showed significant positive associations with tax compliance.p.10
- Business location (β = -0.0177; p = 0.9336) and turnover group (β = 0.0067; p = 0.9432) demonstrated no statistically significant link with compliance levels.p.10
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.