RiskPercept-X: Explainable Transaction-Level Prediction of Investor-Perceived Risk on E-Investment Platforms (International journal of intelligent engineering and systems)
Summary
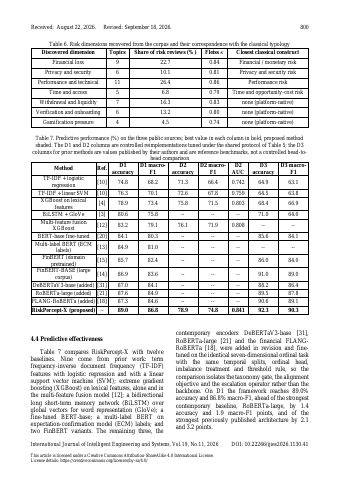
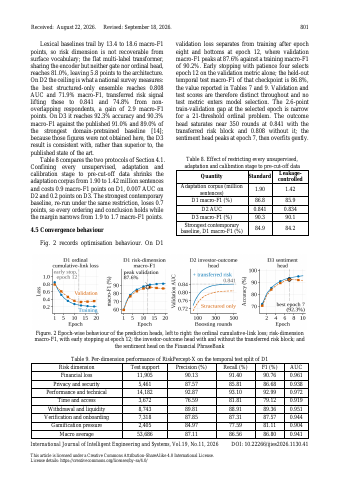
- RiskPercept-X achieves 89.0% accuracy and 86.8% macro-averaged F1 on risk dimensions on a temporally held-out split.p.1
- The framework yields an area under the receiver operating characteristic curve of 0.841 on investor difficulty outcomes.p.1
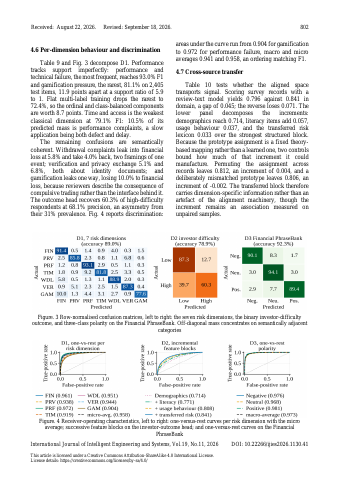
- Evaluation on the Financial PhraseBank benchmark demonstrates 92.3% accuracy.p.1
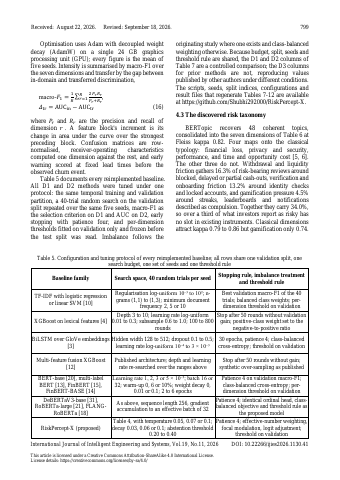
- Three platform-native risk dimensions carry 34.0% of risk-bearing reviews across evaluated applications.p.1
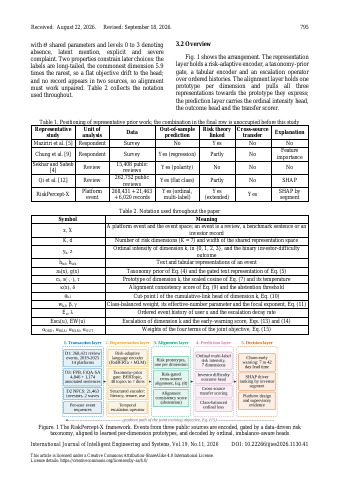
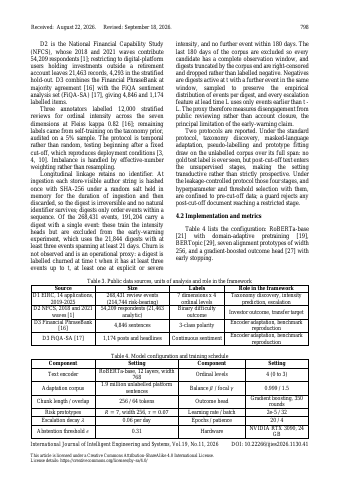
- The e-investment review corpus holds 268,431 review documents from 14 retail brokerage and neobroker applications.p.6
- The National Financial Capability Study analytic dataset contributes 21,463 records of digital-platform users.p.6
Key insights
- RiskPercept-X outperforms the strongest reimplemented baseline by 1.9 macro-F1 points on D1 and 2.9 points on D2.p.1
- Platform-native risk dimensions absent from classical instruments represent 34.0% of risk-bearing user reviews.p.1
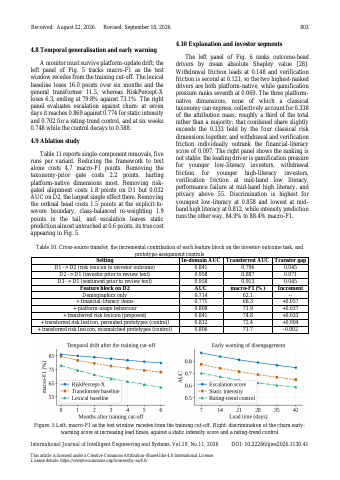
- A leakage-controlled protocol restricting unsupervised and calibration stages to pre-cut-off data reproduces results at 85.9% macro-F1 and 0.834 AUC.p.1
- Temporal escalation scoring enables early warning of user disengagement up to six weeks ahead with an AUC of 0.748.p.11
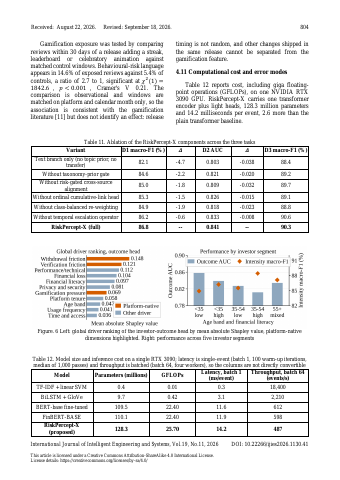
- Withdrawal friction and verification friction serve as the top two drivers of investor-level outcomes with mean absolute Shapley values of 0.148 and 0.121.p.11
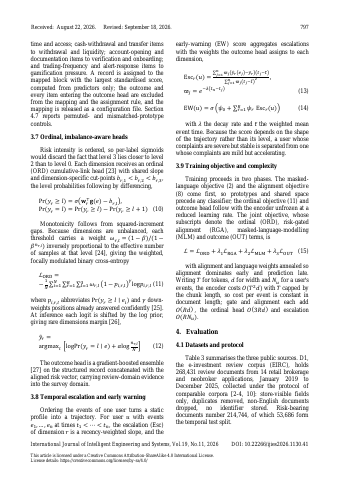
- Ablation testing reveals that removing the taxonomy-prior gate reduces D1 macro-F1 performance by 2.2 percentage points.p.11
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
 p.16
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.