Investor Protection in Sharia and Conventional Securities Crowdfunding: A Comparative Study of SHAFIQ and Santara (Adagium.)
Summary
- OJK Regulation Number 17 of 2025 entered into force on 25 July 2025, revoking OJK Regulation 57/POJK.04/2020 as amended by Regulation 16/POJK.04/2021.p.2
- SHAFIQ received its OJK operating licence under Decision Number KEP-37/D.04/2021 on 19 August 2021 to provide sharia-compliant crowdfunding services.p.2
- Santara obtained its OJK operating licence under Decision Number KEP-59/D.04/2019 on 6 September 2019 as a conventional platform operator.p.2
- Sharia securities crowdfunding relies on DSN-MUI Fatwa Number 140/DSN-MUI/VIII/2021 to establish its contractual compliance framework.p.2
- Information disclosure and clarity of investor rights serve as preventive legal protection mechanisms to prevent disputes before they happen.p.1
- Complaint handling and dispute resolution mechanisms provide repressive legal protection once violations or conflicts occur.p.1
Key insights
- Securities crowdfunding provides capital access for small businesses but exposes investors to risk of loss, share illiquidity, and dividend uncertainty.p.2
- OJK Regulation Number 17 of 2025 governs platform operator duties, securities offerings, contract structures, risk management, and investor protections.p.2
- SHAFIQ structures its sharia securities offerings using musyārakah musāhamah and wakālah contracts.p.2
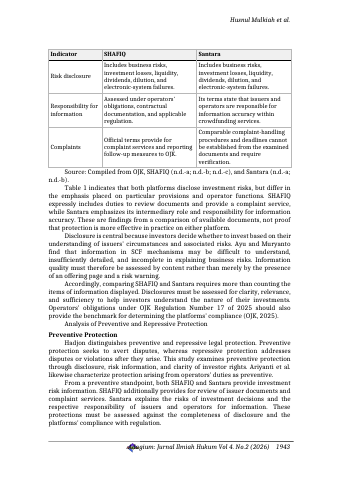
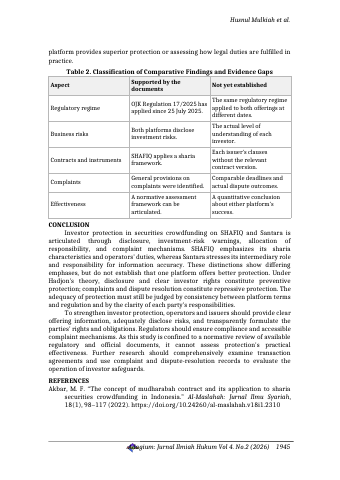
- Both SHAFIQ and Santara disclose investment risks including losses, liquidity constraints, non-payment of dividends, dilution, and system failures.p.7
- Santara emphasizes its role as an intermediary while stating that issuers and operators share responsibility for information accuracy.p.6
- Preventive protection quality depends on readable, complete, and balanced disclosure regarding financial performance and business risks.p.7
- Repressive protection covers dispute resolution through internal platform handling, alternative dispute resolution bodies, or court proceedings.p.8
- Accepting investment risks does not relieve operators or issuers of liability for misleading information or statutory non-compliance.p.8
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.