A Critical Analysis of the Legal and Ethical Challenges of Digital Lending Applications in Tanzania: A Doctrinal Analysis with Comparative Reference to Nigeria (OpenAlex (recherche mondiale))
Summary
- Regulators actively enforced rules by blocking sixty-nine unlicensed loan applications in November 2024.p.3
- Statutory non-compliance penalties under the 2019 Microfinance Regulations range from five hundred thousand to five million shillings.p.7
- Comparative rules in Nigeria enforce penalties reaching up to one hundred million naira or one per cent of turnover.p.7
- Tanzania's Personal Data Protection Commission holds statutory authority to issue enforcement penalties up to one hundred million shillings.p.8
- May 2025 consumer protection amendments mandate a complaint-resolution timeline of fourteen days for credit facilities.p.8
- The Bank of Tanzania can impose a daily penalty of one million shillings for continuous non-compliance with dispute decisions.p.8
Key insights
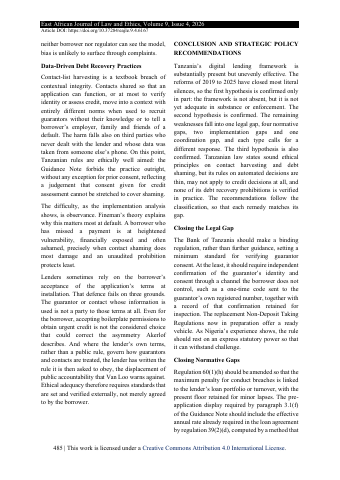
- Tanzanian legal reforms from 2019 to 2025 addressed explicit statutory silences but left significant legal, normative, implementation, and coordination gaps.p.1
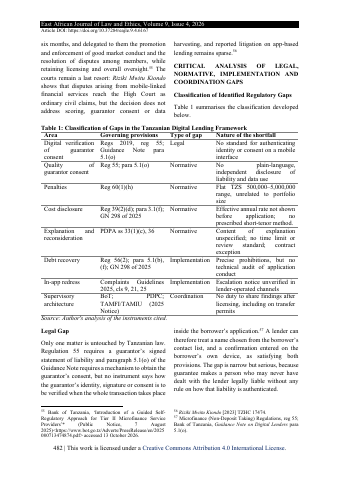
- A critical legal gap exists because no legal standard defines how to verify a guarantor's identity and consent within a mobile app interface.p.9
- Flat administrative penalties under microfinance regulations fail to deter large digital lenders because fine maximums are not tied to portfolio turnover.p.10
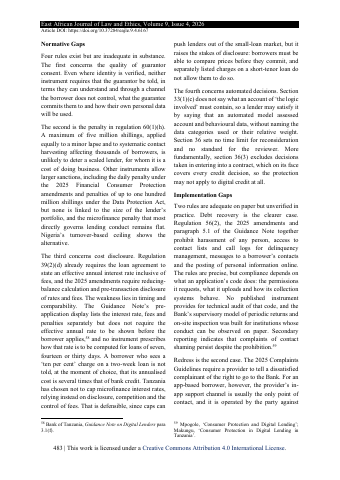
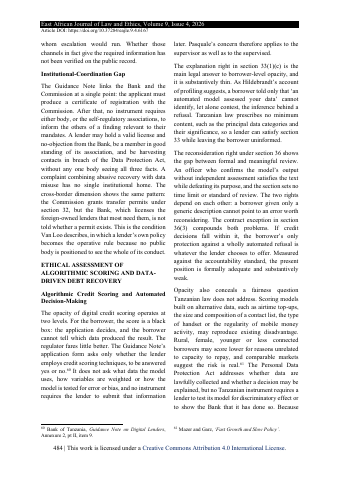
- Automated decision protections under the Personal Data Protection Act are significantly weakened by a broad contract performance exception.p.10
- Mandatory pre-application displays omit the effective annual interest rate for short-tenor loans, preventing meaningful cost comparison by borrowers.p.10
- Regulatory prohibitions against contact harvesting and harassment lack technical audit mechanisms to examine application source code in practice.p.10
- Inter-agency coordination remains fragmented due to the absence of a formal information-sharing memorandum between key financial and data regulators.p.11
Pages
 p.1
 p.2
 p.3
 p.4
 p.5
 p.6
 p.7
 p.8
 p.9
 p.10
 p.11
 p.12
 p.13
 p.14
 p.15
Topics and entities
Summary and figures generated from the document and checked automatically: every number shown appears on the cited page. Publishers can request removal.